Table of Contents
Chris Kwon, CEO of BMC and author of a new book on K-Pop ownership, says the industry has outgrown its “niche music genre” label. He argues K-Pop now functions as a global asset class, one that investors should study like any other sector. His advice: stop reading spreadsheets from a distance and go see the business in person.
Think about that for a second. Would you buy a building without walking through it first? Kwon says entertainment stocks deserve the same treatment, and that idea is reshaping how serious investors approach K-Pop.
K-Pop Is Now a Global Financial Asset
Kwon’s central claim is simple but bold. K-Pop, he says, has moved past being a cultural export and become a measurable, investable asset. You can see this shift in the numbers, the touring revenue, and the sheer scale of fan engagement worldwide.
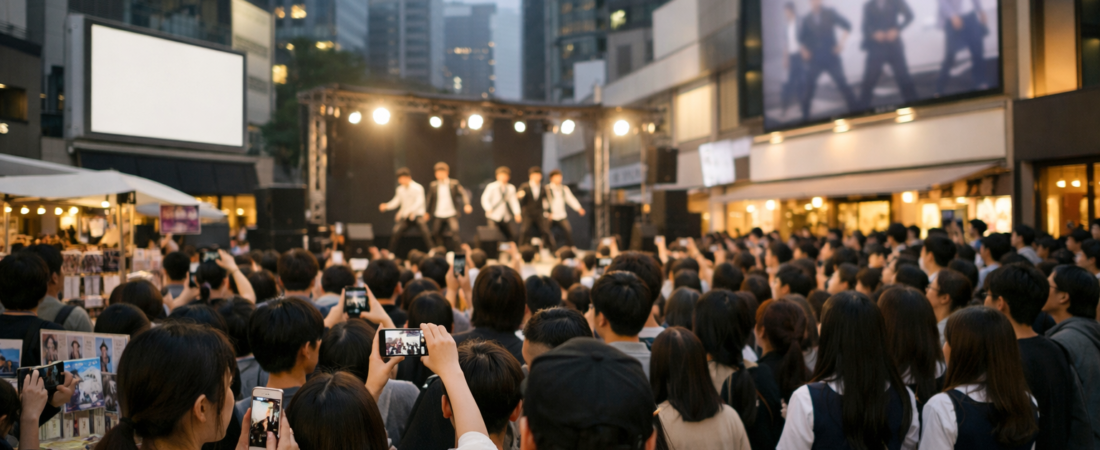
Take BTS. Their massive outdoor concert in Seoul’s Gwanghwamun district this past March drew enormous crowds and global media attention. That single event signaled something important: K-Pop acts now operate like multinational entertainment conglomerates, not just bands with record deals.
This matters for anyone watching Korean markets. Entertainment companies listed on the KOSPI and KOSDAQ have become more than music labels. They are increasingly treated as IP-driven businesses with diversified revenue streams, and K-Pop sits at the center of that transformation.
For readers outside Korea, this trend is worth tracking. K-Pop’s growth mirrors how Hollywood studios or global sports leagues built value through franchises, not single products. Understanding this parallel helps explain why global funds are paying closer attention to Korean entertainment stocks.
Why “Site Visits” Matter in K-Pop Investing
Kwon uses a real estate term, “imjang,” which roughly means an on-site property inspection. In Korea, nobody buys an apartment without visiting it first. He argues entertainment investors should apply the same discipline.
What does that look like in practice? It means actually attending concerts, watching fan interactions, and observing how companies manage their artists day to day. Numbers alone, Kwon warns, can hide the real health of a business.
Why does this matter so much for K-Pop specifically? Because the value of an entertainment company often lives inside intangible things, like fan loyalty and brand trust, that don’t always show up cleanly on a balance sheet. You have to watch the crowd to understand the asset.
This is where Kwon’s approach gets practical. He suggests investors examine ticket sales patterns, merchandise lines, and how fandoms behave across different countries. A company’s true growth potential often appears first in these ground-level signals, long before it reaches quarterly earnings reports.
(Imagine judging a restaurant’s quality by its menu alone, without ever tasting the food. That’s essentially what spreadsheet-only investing in K-Pop risks doing.)
Fandom, IP, and the Business Behind the Music
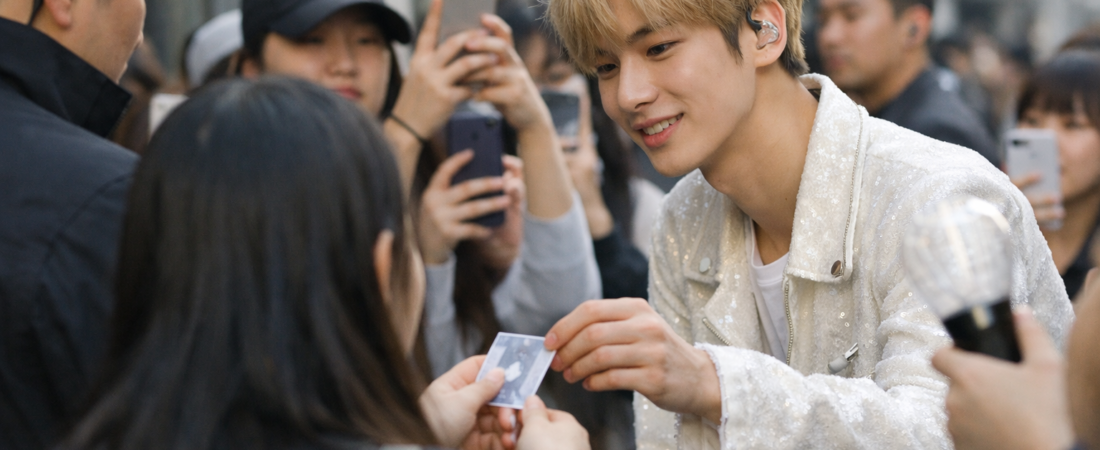
Fandom is the engine that drives K-Pop’s economic model. Fans don’t just buy albums anymore; they buy concert tickets, fan merchandise, photo cards, and streaming subscriptions across multiple platforms. This layered spending creates a revenue structure unlike traditional Western music industries.
Intellectual property, or IP, expansion is the second pillar Kwon highlights. Companies now extend artist brands into webtoons, games, animation, and even virtual idols. K-Pop labels increasingly resemble entertainment studios managing franchises, much like how a film studio builds a cinematic universe around one character.
You might ask: isn’t this just marketing dressed up as finance? Not quite. According to Maeil Business Newspaper, this IP-driven structure is exactly what separates sustainable entertainment companies from short-term hit machines in the K-Pop market.
Global comparisons help clarify this point further. Disney built decades of value by controlling characters across films, theme parks, and merchandise. K-Pop agencies are now attempting something similar, turning individual artists into lasting brands that generate income long after an album cycle ends.
What This Means for K-Pop Investors Today
So should you rush out and buy entertainment stocks tomorrow? Not necessarily. Kwon’s real message is about mindset, not a quick trading tip.
He wants investors to understand the ecosystem, including touring logistics, fandom economics, and global IP strategy, before committing capital. K-Pop’s growth story is real, but it still carries risk tied to artist contracts, public controversies, and shifting fan loyalty.
Here’s an honest truth worth sitting with. The same fandom passion that fuels K-Pop’s billion-dollar growth can also turn fragile overnight, when a scandal breaks or an idol group disbands. Yet that same passion has also built genuine cross-border communities, connecting teenagers in Seoul, Sao Paulo, and Seattle through shared joy rather than division.
Markets reward companies that manage this tension well, building loyalty without exploiting it, and investors who notice this balance early often see it before the numbers do. That balance between fragility and connection is exactly what makes K-Pop such a compelling, and complicated, asset to study.
Looking ahead, K-Pop’s influence on Korean capital markets will likely keep growing. More companies will chase IP expansion, and more global investors will apply Kwon’s “go see it yourself” philosophy to entertainment stocks. The winners will probably be the ones who treat fandom as data, not just noise.
What do you think about treating K-Pop as a serious financial asset rather than just a cultural trend?
AI-Generated Photorealistic Image — All people, scenes, and details in this image are entirely AI-generated and fictional. Not a real photograph of an actual person or event. 이 이미지는 AI로 생성된 가상 이미지입니다.
Leave a Reply